
Buying a Home in Roseville, CA: A Step-by-Step 2026 Guide
Updated on: October 29, 2026
What to know before buying a home in Roseville
Buying a home in Roseville, CA, is a California escrow purchase in Placer County: you get pre-approved, make an offer on a state purchase agreement, clear inspections and appraisal during the contingency period, and close through escrow. The city sits in the Greater Sacramento area.
Key takeaway
Roseville purchases follow California's standard escrow process, but local costs can raise your monthly payment:
- Mello-Roos special taxes in many newer neighborhoods
- HOA dues
- Insurance priced on wildfire risk
Check those costs before you make an offer. Once your offer is accepted, the contingency deadlines decide whether you can walk away with your deposit.
Who this guide is for
This guide is for anyone buying a home in Roseville, CA, especially first-time and relocating buyers, who wants the steps and local costs in order.
Related guides: Roseville, CA housing market, Best real estate agent in Roseville, Best neighborhoods in Roseville, Pros and cons of living in Roseville, Sell my home in Roseville, First time home buyers Roseville.
Buying a home in Roseville at a glance
- Mello-Roos can lift a newer home's total tax rate near 1.8%.
- Minimum down: 3% conventional, 3.5% FHA, 0% VA.
- 2026 Placer County loan limits: $832,750 conforming, $764,750 FHA.
- Default contingencies: 17 days inspection and appraisal, 21 days loan.
- File the $7,000 homeowners' exemption within 30 days of supplemental notice.
Step 1: Get pre-approved and price the full monthly payment
Get a lender pre-approval before you tour homes. The lender reviews your income, assets, debts and credit and states how much it will lend, which shows sellers you can close. Ask for an updated letter if your search runs long or your finances change.
The City of Roseville's economic development data, updated June 2026, lists a median sale price of $631,000. Recent sales of comparable homes tell you more about a specific listing than that citywide figure does. For income context, the U.S. Census Bureau puts the city's median household income at $119,288 (2020 to 2024 American Community Survey, in 2024 dollars).
Your loan type sets the minimum down payment:
- Conventional: as little as 3% down for qualified first-time or primary-residence buyers. These loans generally price best for buyers with strong credit.
- FHA: 3.5% down. The low minimum helps buyers with less saved.
- VA: zero down for eligible veterans and service members.
Putting 10% down is a common middle option, and anything under 20% usually means paying mortgage insurance. In 2026, a Placer County loan above $832,750 is a jumbo loan, and FHA loans top out at $764,750. A home priced near those amounts needs a larger down payment or a different loan.
The payment a lender qualifies you on includes principal, interest, property tax, any Mello-Roos special tax, HOA dues and homeowners insurance. Set your target payment below your maximum approval so repairs, ongoing maintenance and savings still fit. Lenders compare that payment plus your other debts to your income. Running the same debt-to-income math yourself shows how much house you can afford before you shop. Mortgage rates move daily, so compare quotes from two or three lenders on the same day.
For a buyer entering this market for the first time, CalHFA has two programs to ask your lender about:
- Dream For All Shared Appreciation Loan: offers first-generation homebuyers up to 20% of the purchase price or appraised value toward the down payment. It reopened applications on February 24, 2026.
- MyHome Assistance Program: a year-round deferred second loan for down payment or closing costs. It is another of the homebuyer assistance programs available.
Budget for the cost of living in Roseville beyond the mortgage, including utilities, transportation and groceries, before you settle on a payment.
Step 2: Check Mello-Roos, property tax, HOA and insurance costs before you offer
A Community Facilities District, known as Mello-Roos, levies a special tax on top of regular property tax. The tax pays for roads, parks, schools and other infrastructure in newer neighborhoods, and many of the newer developments in west Roseville carry it. Estimates for the 2026-27 tax year put the total effective property tax rate at about 1.1% in older neighborhoods. In newer developments with heavy Mello-Roos and infrastructure bonds, it reaches roughly 1.8%.
Before you offer, ask the listing agent for the property's Notice of Special Tax or the seller's latest tax bill. Under California Civil Code Section 1102.6b, the seller must make a good-faith effort to get this notice from each agency levying the tax and deliver it to you. The agency prepares the notice. It lists:
- The district name
- The current annual tax
- The maximum tax that can be levied
- The allowed yearly increase
- When the tax ends
If the notice reaches you after you sign the purchase agreement, Civil Code Section 1102.3 lets you cancel with written notice to the seller or seller's agent. The deadline is three days after in-person delivery or five days after delivery by mail. If you agreed to transact electronically, it is five days after electronic delivery.
Under Proposition 13, Placer County reassesses the home at your purchase price when ownership changes, so budget property taxes from that price rather than the seller's current bill. Afterward, the assessed value can rise no more than 2% a year, and the base rate is 1% plus voter-approved bonds.
HOA fees vary by community:
- 55+ communities: generally about $170 to $250 a month. Sun City Roseville's regular assessment is about $225; newer Heritage Solaire runs about $280 to $289.
- Condos and townhomes in master-planned communities: generally $300 to $450 a month.
Get a homeowners insurance quote before you remove contingencies. The City of Roseville's Fire Hazard Severity Zone lookup map, built on CAL FIRE data, rates parcels within city limits as Non-Wildland, Moderate, High or Very High. The city says insurers are unlikely to use those designations directly. However, insurers' own risk models likely draw on much of the same vegetation, terrain and fire-weather data.
Step 3: Narrow your search by price, home type and location
Set your filters from the price band in Step 1 and the full monthly cost, including any special tax from Step 2. Then decide on:
- Resale or new construction
- Lot size
- Whether you will accept an HOA
- Which commute routes matter
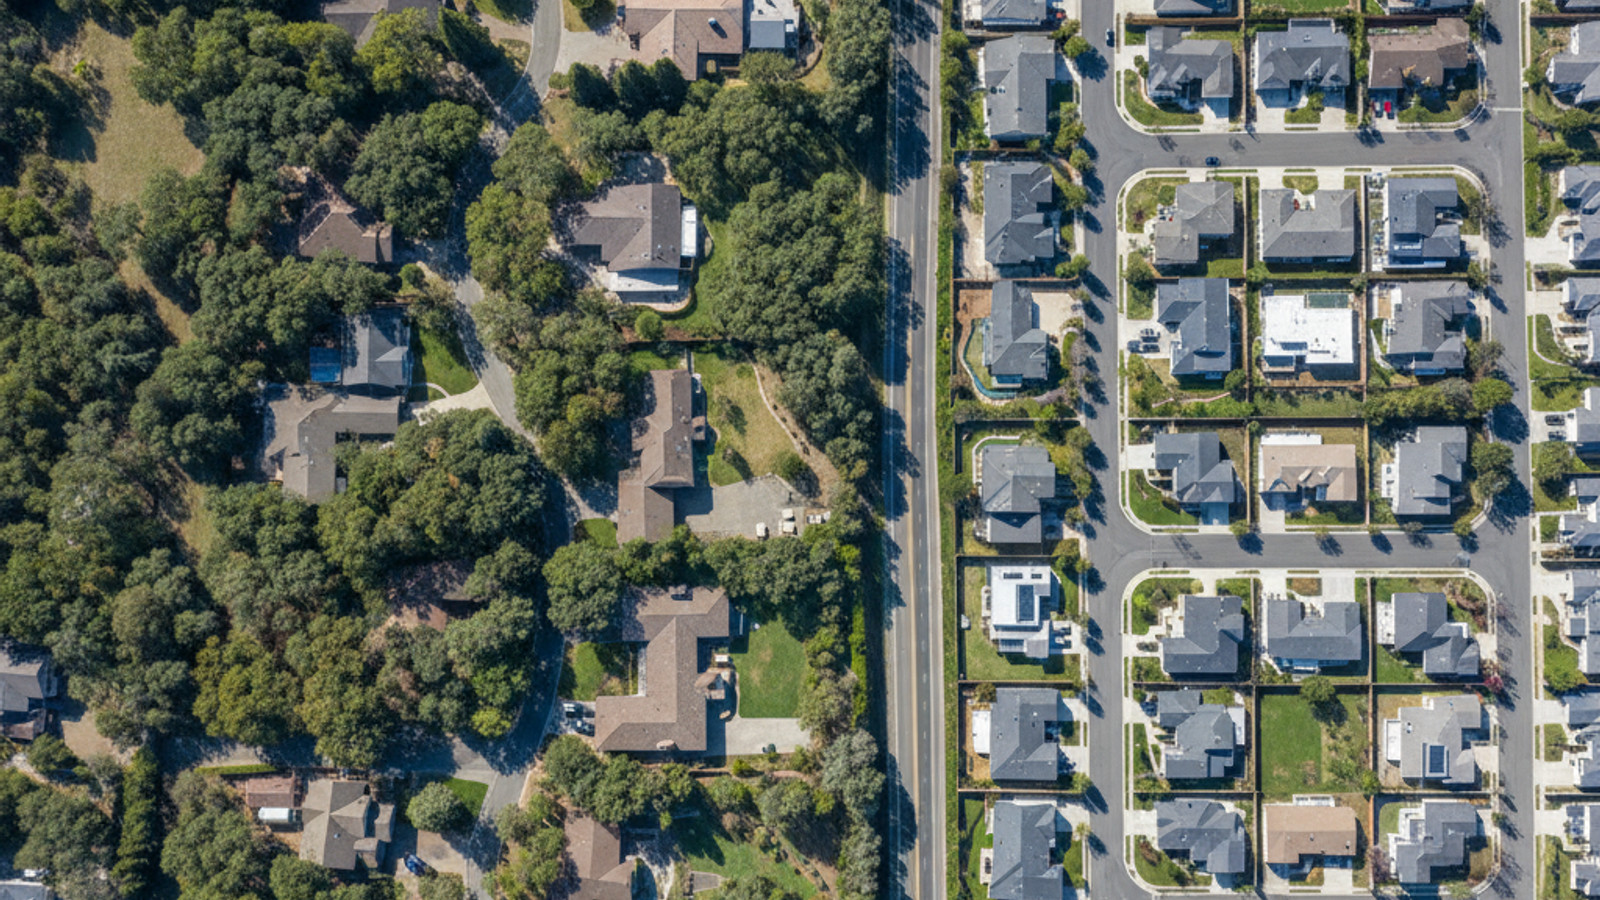
The east side and the Granite Bay edge have established homes with mature oaks and larger lots. West Roseville has master-planned communities with new construction. Age-restricted (55+) communities, such as Sun City Roseville and Heritage Solaire, are a separate home type with their own HOA rules.
Neighborhood comparisons are most useful when they line up lot size, home age, HOA status and special taxes side by side. Condos and townhomes are usually Roseville's lowest-priced entry point, and larger detached homes the highest.
Before you commit to a part of town, drive your commute on I-80 and SR-65 at rush hour, for example, to Sutter Roseville Medical Center. Pay more for quick freeway access only if you will use it daily. Visit your shortlisted areas in person on a weekday and a weekend to check traffic, noise and nearby construction.
Roseville school districts and how to verify a home's boundaries
Five school districts serve the city of Roseville:
- Roseville City School District: transitional kindergarten through eighth grade.
- Roseville Joint Union High School District: grades nine through twelve.
- Center Unified School District: TK-12, serving parts of the city instead.
- Eureka Union School District: K-8, serving parts of the city instead.
- Dry Creek Joint Elementary School District: TK-8, serving parts of the city instead.
Before you make an offer, enter the exact address in the City of Roseville's Know Your Boundaries lookup or the district's own locator. Listing descriptions can name the wrong school, and boundaries and enrollment capacity can change, so confirm the assignment with the district. Then look up that specific assigned school on the California School Dashboard.
Step 4: Hire a buyer's agent and sign the written agreement
A buyer's agent:
- Sets up your search
- Pulls comparable sales
- Writes the offer and negotiates
- Tracks contingency deadlines
- Coordinates inspections and escrow
California requires a signed written agreement between you and the agent before the agent works with you. Before you sign, read how long it lasts, how it can end and what it says about the agent's pay.
Buyer-agent commissions are negotiable. The agreement can have you pay directly or ask the seller to cover the cost as a concession. When choosing a local agent, ask three things:
- How many Roseville buyers have they represented recently?
- How do they handle multiple offers?
- How, and how often, will they update you during the search and escrow?
You can keep your own agent on a for-sale-by-owner home or a new-construction purchase. A for-sale-by-owner seller may decline to pay your agent, so settle in the agreement who pays.
Step 5: Make an offer that fits the market
The spring 2026 housing market in Roseville left little room for slow offers: when properly prepared, properties frequently sell for 99% to 100% of list price, and well-priced homes left the MLS within days.
On the California Residential Purchase Agreement, the terms that decide your risk are price, contingencies and deposit. Unless you and the seller agree in writing to other numbers, you have:
- 17 days from acceptance to complete inspections
- 17 days to remove the appraisal contingency
- 21 days to remove the loan contingency
Your earnest money deposit goes into escrow within three business days of acceptance. It typically runs from 1% of the price up to the same share as the lowest conventional down payment.
Shortening or waiving contingencies makes an offer stronger, but if a problem appears after you remove one, your deposit is at risk. California Civil Code Section 1675 limits that risk on a home of one to four units you plan to live in. A liquidated-damages amount the seller keeps is presumed valid only up to that top-of-range share of the purchase price. Above that, the seller must prove the amount is reasonable.
Cash offers and large down payments remove the loan risk sellers worry about. Terms beyond price also count: a closing date or rent-back that fits the seller's plans can strengthen your offer without raising the price.
Builders work differently:
- Ask before your first visit how the builder registers a buyer's agent, since your agent may need to be named from the start.
- Read the builder's own purchase contract and deposit terms instead of assuming the state form's periods apply.
- Compare any incentive tied to the builder's preferred lender against an outside loan quote.
Step 6: Inspections and appraisal during the contingency period
Book the general inspection right after acceptance so the report arrives inside the investigation period from Step 5. It covers the roof, foundation, plumbing, electrical and HVAC. The inspector may recommend specialty inspections:
- Wood-destroying pest: termites and dry rot.
- Roof: remaining life and leaks.
- Sewer line: a camera check of the line to the street.
- Pool and chimney: equipment, surfaces and safety.
After the reports, you can request repairs, ask for a credit or price reduction, or cancel within the contingency. California seller disclosures arrive in writing. Read them before the investigation period ends, because that is your window to act on what they reveal. If the home has an HOA, review the association's budget, reserves and rules during escrow.
The lender orders an appraisal. If it comes in below your price, you can renegotiate, cover the gap in cash, or cancel under the appraisal contingency. Before you remove contingencies, bind the insurance policy you priced in Step 2.
Step 7: Closing day and what to do after you get the keys
Buyer closing costs appear on your Loan Estimate and final Closing Disclosure. They include lender, title, escrow and recording charges plus prepaid property tax and insurance. Your purchase agreement sets the closing date. Financed purchases need time for underwriting and the appraisal, while cash purchases can close sooner. The escrow and title companies prepare and record the documents. Your part:
- Answer lender requests fast: send income, tax-return and bank-account documents promptly so underwriting finishes before the loan contingency deadline.
- Keep finances steady: no new credit or job changes until the loan funds.
- Review the Closing Disclosure: compare its interest rate, loan term, monthly payment and cash to close with your Loan Estimate, and ask about any difference before you sign.
- Final walkthrough: confirm agreed repairs and the home's condition.
- Wire safely: confirm wiring instructions by phoning the escrow officer at a number you already have, never one from an email.
After the loan funds and the deed records, you get the keys. Two tasks follow:
- Homeowners' exemption: In 2026, it cuts a qualifying home's assessed value by up to $7,000, about $70 a year. You qualify if you will occupy the home as your main residence within 90 days of purchase. Filing within 30 days of the Notice of Supplemental Assessment gets the full exemption. Filing later, before the first supplemental installment is delinquent, gets 80%. In later years, the annual deadline is February 15.
- Supplemental tax bill: Expect the notice six to twelve months after the transfer. A purchase from June 1 to December 31 brings one supplemental bill; a purchase from January 1 to May 31 brings two. The bills come to you, not through your lender's impound account, so call your lender to decide who pays.
Moving to Roseville goes more smoothly if you book movers and schedule utility transfers for your closing date as soon as you remove contingencies.
Frequently asked questions
Are all homes with a Roseville address inside Roseville city limits and Placer County?
No. Some homes in unincorporated Placer County use a Roseville mailing address, because the Postal Service assigns city names and ZIP codes for delivery efficiency rather than by city limits. Those homes are served by agencies such as the Placer County Sheriff's Office, South Placer Fire District, and SMUD or PG&E instead of Roseville police, fire and Roseville Electric. Confirm the parcel's jurisdiction on the Placer County assessor record before you offer.
How much cash should I have ready, and when is each payment due?
The earnest money deposit comes first, within the Step 5 deadline, and inspection fees follow during the contingency period. The down payment and closing costs are due at closing, and lenders may also want reserves left in your accounts afterward.
How long does it take to buy a home in Roseville?
Pre-approval usually takes days, and the search depends on you and on how many homes are for sale. After acceptance, the contingency periods from Step 5 run inside escrow, which ends on the closing date set in your purchase agreement.
Can I buy a home in Roseville before I sell my current one?
An offer contingent on selling your home is weaker when competition is high. You can buy first with bridge financing or home equity if the lender approves carrying both payments, or sell first and negotiate a rent-back. Ask your lender which option it will approve before you write an offer.
Should I buy new construction or resale in Roseville?
New construction more often carries the special tax and builder contract terms covered above, so hire an independent inspector anyway. Resale homes offer established lots and room to negotiate through disclosures and inspection.
Homes for sale in Roseville
Free market report
Want the full market report for Roseville?
We want to ensure that you have all the information needed to make the best decisions about your home goals. When you enter your info in the form you will get instant access to the area's latest market report, complete with sales trends.
Roseville
Market Report
Schools in the area
Around the area
News and advice
Read helpful resources and articles related to the area.
Who Is the Best Realtor in Rocklin, CA? ...
Cash Buyers Are Making Moves: What Today's Housing ...
Cash or mortgage, finding the right home starts with the right information! Download the Made 4...
Owe More on Your Mortgage Than Your Home's ...
Owe more on your mortgage than your home is worth? Our Greater Sacramento team explains how...
Ready to take
The next step?
Not sure if now's the right time to buy or sell? Need a reliable contractor? We would love to get to know more about you and your needs! Feel free to use any of the options here to get in contact with us!
Sources
- Placer County: Proposition 13
- Placer County: Homeowners' Exemption
- Placer County: Supplemental Tax Estimator
- City of Roseville: Know Your Boundaries
- City of Roseville: Fire Hazard Severity Zones
- City of Roseville: Economic Development Data
- California Civil Code Section 1102.3
- California Civil Code Section 1675
- C.A.R. Standard Forms
- CalHFA press release, January 16, 2026
- U.S. Census Bureau QuickFacts: Roseville city, California
- California Loan Limits 2026
Homes for Sale in Roseville
Free market report
Want the full market report for Roseville?
We want to ensure that you have all the information needed to make the best decisions when it comes to your home goals. When you enter your info in the form you will get instant access to the area's latest market report, complete with sales and demographic trends.
Roseville
Market Report
News and Advice
Read helpful resources and articles related to the area.
Sacramento Down Payment Assistance With No Income Limits
Higher rates are squeezing budgets. Our team is helping Sacramento buyers access a down payment assistance…
Selling Your Home in Today's Market? 3 Pricing …
Planning to sell? Download the Made 4 More app to explore accurate listings and make smarter…
Housing Market Crash in 2027? 3 Real Estate …
Skip the scary headlines! Download the Made 4 More app for accurate home listings, great deals,…
Ready to take
The next step?
Not sure if now's the right time to buy or sell? Need a reliable contractor? We would love to get to know more about you and your needs! Feel free to use any of the options here to get in contact with us!