
Don’t let hidden fees or bad listings cost you. Download the Made 4 More app for accurate listings, no hidden fees, and no selling your personal info. Find your dream home with confidence!
Buying a home is exciting. Watching your monthly expenses climb? Not so much.
Between mortgage payments, property taxes, and home insurance, owning a home can get expensive fast. And lately, insurance premiums have been taking a bigger bite out of homeowners’ budgets.
But here’s some good news: You could save around $440 a year on home insurance just by shopping around. That’s money you could put toward home improvements, savings, or something you actually enjoy.
Let’s break down what’s happening with home insurance costs and how you can keep more money in your pocket.
Home Insurance Costs Are Still Rising, But There’s Good News
Home insurance has become a bigger part of the monthly mortgage payment, accounting for approximately 9.6% of the average payment, according to Intercontinental Exchange.
The good news? Premium increases are finally slowing down.
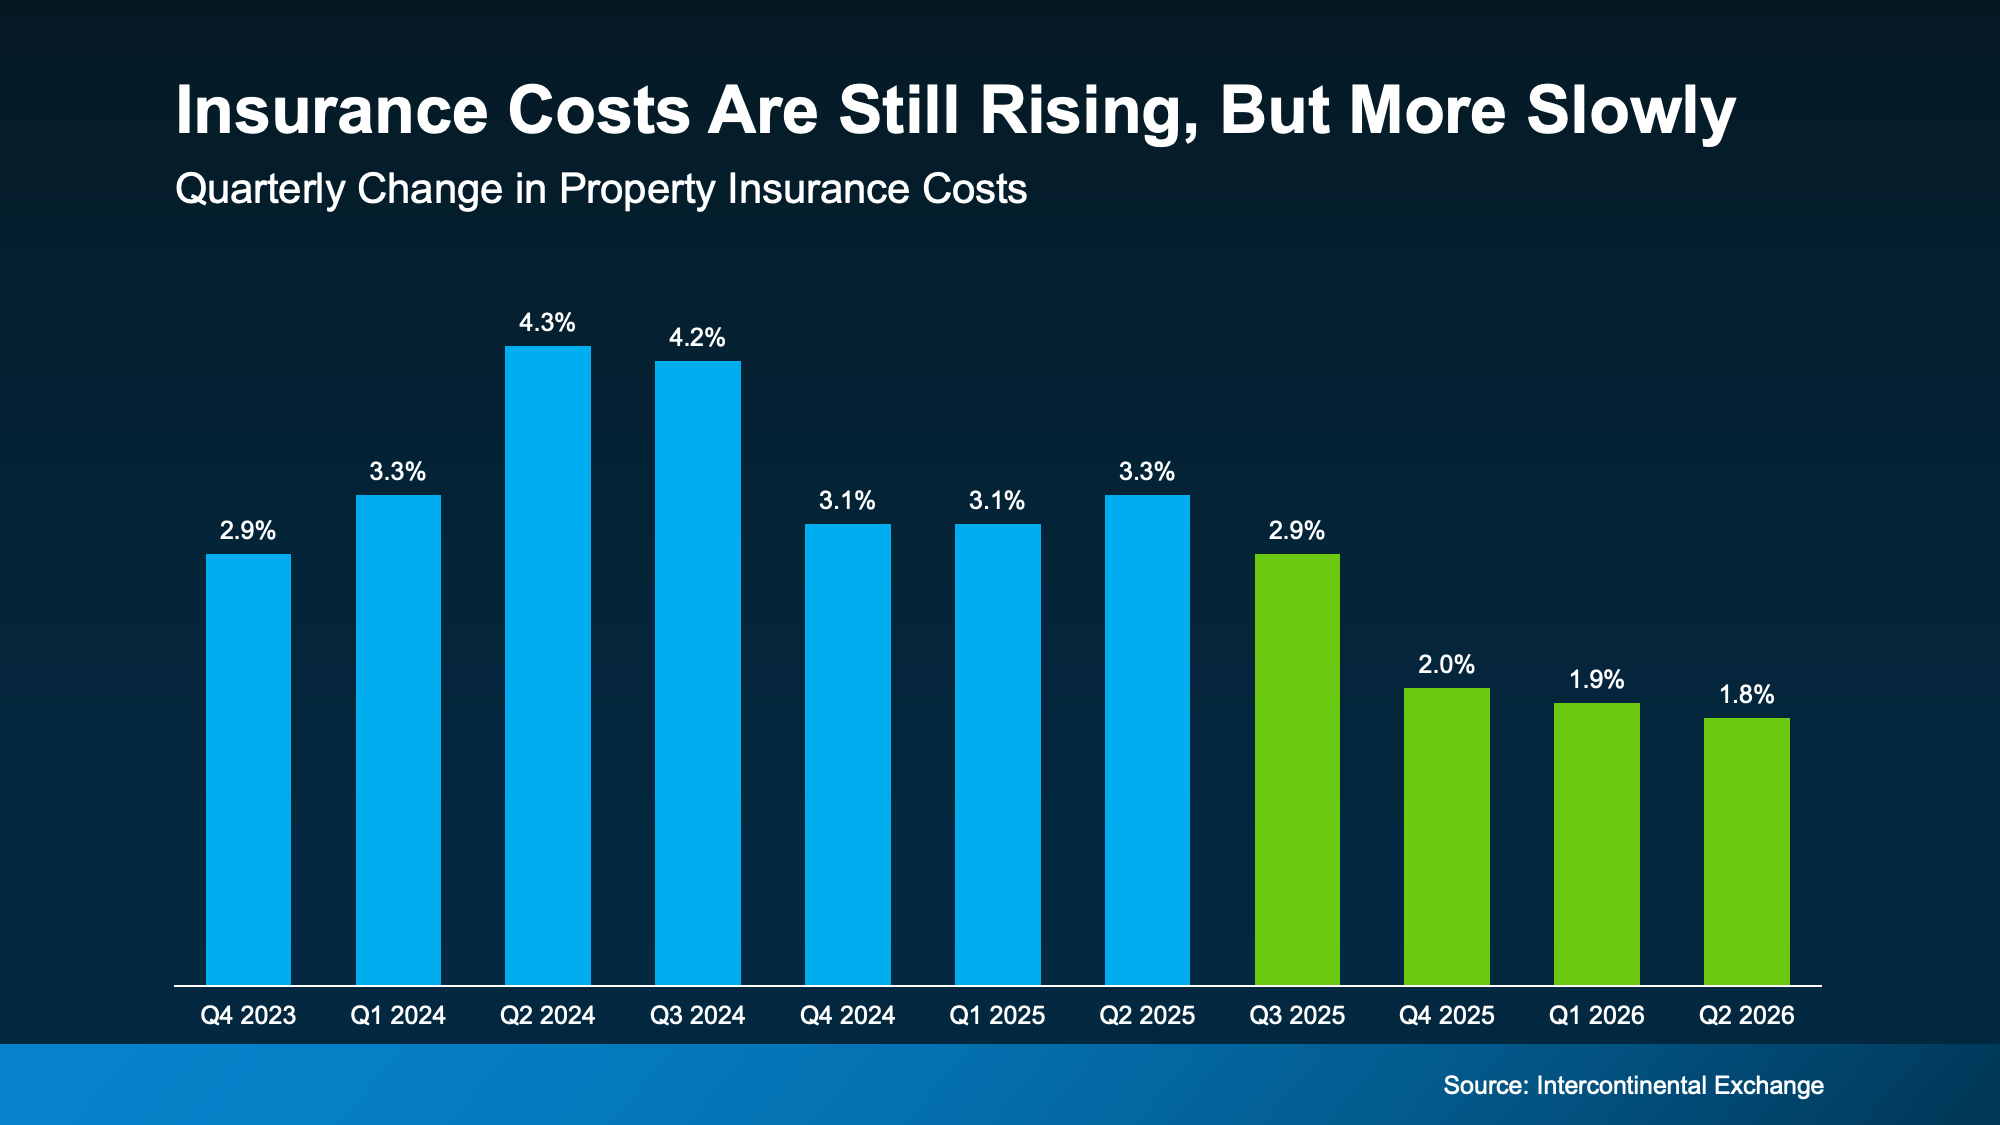
In mid-2024, home insurance premiums jumped 4.3% in just one quarter. By the second quarter of this year, that increase had slowed to 1.8%—the smallest quarterly increase in nearly three years.
Does that mean insurance is getting cheaper? Not exactly. But it does mean homeowners may finally be getting a little breathing room.
The $440 Savings Move Most Homeowners Should Consider
Here’s where things get interesting.
According to Intercontinental Exchange, homeowners who switched insurance providers after shopping around saw their premiums drop by an average of 6.6%.
Meanwhile, homeowners who stayed with their existing insurance company experienced an average increase of 10.4%.
That difference adds up to approximately $440 in annual savings for homeowners who switched.
And here’s the best part: Those savings didn’t come from sacrificing coverage.
In fact, homeowners who switched saw their deductibles decrease by 1.4%, while their coverage limits increased by 7.3%.
The takeaway? You don’t always have to pay more to get better protection.
Before renewing your policy, compare quotes from several insurance providers. You might discover a better deal waiting for you.
Buying a Home? The Property You Choose Could Save You More
Your insurance costs don’t depend entirely on your insurance company. The home itself matters, too.
According to John Burns Research and Consulting, newly built homes are generally 10% to 15% less expensive to insure than older homes nationwide.
Why? Newer homes often have updated electrical systems, modern plumbing, newer roofing materials, and construction features designed to meet current building standards.
Of course, a new construction home isn’t the right fit for everyone. But if you’re considering one, lower insurance costs could be another reason to put it on your shortlist.
When you’re comparing homes, look beyond the purchase price. Your long-term monthly expenses matter just as much.
3 Smart Ways to Keep Home Insurance Costs Under Control
Want to avoid paying more than necessary? Start with these simple moves:
- Compare insurance quotes: Don’t automatically renew with the same provider. Shop around and see what’s available.
- Review your coverage annually: Make sure your policy still fits your home, finances, and needs.
- Explore newer homes: If you’re open to new construction, compare insurance costs alongside the purchase price and other expenses.
A little research now could make a real difference to your budget later.
The Bottom Line: Small Savings Can Make a Big Difference
Home insurance might be getting more expensive, but that doesn’t mean you’re stuck paying whatever your current provider charges.
Whether you’re buying your first home or preparing for your next move, knowing how to manage insurance costs can help you make a smarter financial decision.
Want to find a home that fits your budget without sacrificing your goals? Call or text us at 855-935-MORE.
Check out this article next